TCIL Q2 FY27 profits remain resilient, with PBT* at Rs. 848 Mn despite global headwinds.
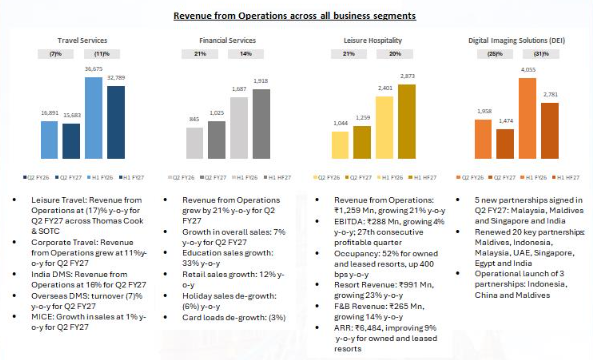
Mumbai, 2nd November 2026 · Financial Services segment delivered a strong growth of 21% y-o-y for Q2 FY27 and 14% y-o-y for H1 FY27 in Revenue from Operations, with Education and Corporate segments contributing well. · India
Mumbai, 2nd November 2026
· Financial Services segment delivered a strong growth of 21% y-o-y for Q2 FY27 and 14% y-o-y for H1 FY27 in Revenue from Operations, with Education and Corporate segments contributing well.
· India Travel Businesses staged a sharp recovery despite the slow start in July, ending the quarter just 6% lower than last year & EBIT margins at a healthy 3.8%. Domestic and Short Haul segments led the growth.
· Overseas Destination Management Services (DMS) business revenue recovered during the quarter despite the continued impact of the West Asia conflict. The effect of the conflict impacted operations in specific geographies, resulting in a drop in Revenue from Operations and EBIT margin for the segment.
· Healthy forward bookings of 30% for the current quarter (Q3 FY27) for the India leisure travel business, signal positive future demand trends, despite elevated airfares and other input costs.
Consolidated Financial Performance
· PBT* for Q2 FY27 held firm at Rs. 848 Mn. Vs Rs. 845 Mn in Q2 FY26
· Total Income for Q2 FY27 stood at Rs. 20,030 Mn, (5) % y-o-y; H1 FY27 stood at Rs. 41,560 Mn, (9)% y-o-y
· The Group continues to maintain a strong financial position, with Cash & short-term investments at Rs. 28, 430 Mn as of September 30, 2026 vs Rs. 26,488 Mn as of June 30, 2026
· CRISIL has reaffirmed the rating of ‘CRISIL AA/Stable’ on the long-term bank facilities of TCIL and ‘CRISIL A1+’ rating on the short-term bank facilities and short- term debt of the company
Financial Services
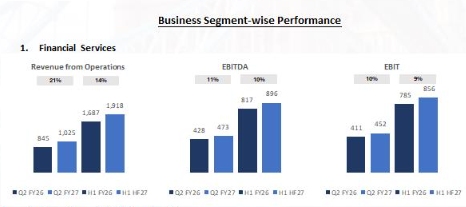
· Revenue from Operations increased by 21% y-o-y for Q2 FY27 and 14% y-o-y for H1 FY27
· EBIT grew by 10% for Q2 FY27 and 9% for H1 FY27
· Overall retail sales grew by a healthy 12%, driven by a strong 33% growth in Education, despite a decline in the segment nationally.
Travel Services
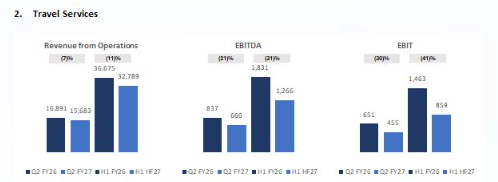
· India Travel Businesses staged a sharp recovery despite the slow start in July and ended the quarter with a reduced gap of 6% Vs last year & EBIT margins at a healthy 3.8%. Domestic and Short-Haul segments led the growth.
· The India DMS business grew 16% in a seasonally softer quarter, supported by steady inflows from key source markets like UK, Germany, France, Portugal & Japan.
* PBT excludes exceptional items
· International DMS businesses in specific geographies continue to be impacted due to geopolitical factors USA (ATP) and GCC region (Desert Adventures).
· Healthy forward bookings of 30% for the current quarter (Q3 FY27) for the India leisure travel business, signal positive future demand trends, despite elevated airfares and other input costs.
Leisure Hospitality (Sterling Holidays & Nature Trails)
· 83 Resorts as of September 2026, up by 20% y-o-y
· 7 Resorts opened in Q2 FY27 (Highest for a quarter) – Jagdalpur, Sattal, Agra, Varanasi, Corbett, Tadoba and Jawai
· Occupancy & ARR also improved by 52% and 9% y-o-y, respectively
· Nature Trails saw a doubling of resorts from 3 to 6 with a 10% increase in revenue, 79% increase in room inventory and 19% increase in guest ratio on a y-o-y basis. Agreements for 3 more resorts have been signed to go on stream in the current quarter.
Digital Imaging Solutions (DEI)
· While DEI continued to be impacted by geopolitical headwinds, cost containment measures initiated in Q1 FY27 helped narrow its losses significantly, from Rs 208 Mn to Rs 76 Mn in Q2 FY27
Commenting on the results, Mahesh Iyer, Managing Director & CEO, Thomas Cook (India) Limited, said, “Q2 FY27 again demonstrated the resilience of the TCIL Group with PBT* holding firm at Rs. 848 Mn despite the continued impact of the West Asia conflict. Disciplined execution with a clear focus on margins, helped us offset some shortfall in the travel business. Looking ahead, we are optimistic of continued momentum in India leisure travel, with forward bookings trending at a healthy 30% growth over last year – even in the face of elevated airfares and other input costs. This is a positive signal for the current quarter and beyond”

Forex business through digital touchpoints:
· WhatsApp: Transactions grew over 3% y-o-y, with 798+ in Q2 FY27 vs 774 in Q2 FY26
· App bookings: 4x growth y-o-y in Q2 FY27 with +939 transactions vs 236 in Q2 FY26
· Website bookings: 99% y-o-y in Q2 FY27 with +1013 transactions vs 1022 in Q2 FY26
· Video KYC: Transactions were at an all-time high in Q2 FY27 with 5191+ transactions vs 186 in Q1 FY26
· Digital adoption (DFC + FX Mate) is at 22.4% y-o-y in Q2 FY27 vs 22.7% in Q2 FY26
· Retail: Operationalized retail counters at Angamaly, Cochin and Hubli while closing branches in Thiruvananthapuram as part of the retail network optimization during the quarter.
Corporate Travel
· Secured new corporate travel accounts across the Pharmaceuticals & Healthcare, Auto Components, FinTech & Digital Payments and Information Technology (IT) sectors in Q2 FY27
· Total Air and Non-Air volumes grew by 18.15% y-o-y in Q2 FY27, reflecting sustained momentum across corporate travel segments
· Air volumes recorded growth of 18.2% y-o-y during Q2 FY27
· Domestic Air volumes increased by 22.7% y-o-y, driven by continued growth in business travel demand across India.
· International Air volumes grew by 15.26% y-o-y, underlining strong demand for cross-border corporate travel.
· Hotel volumes increased by 81.83% y-o-y, making accommodation one of the fastest-growing segments within the Company’s corporate travel portfolio.
· Hotel transactions grew by 36.5% y-o-y, reflecting increasing adoption of managed accommodation programs by corporate clients
· Non-Air volumes and transactions recorded q-o-q growth of 19.2% and 19.9%, respectively, demonstrating continued expansion of the Company’s diversified travel services portfolio.
Meetings-Incentives-Conferences-Exhibitions (MICE)
· Managed over 176 groups ranging from 50 to 7000 delegates per group.
· Key international destinations: Switzerland, Italy, the United Kingdom, Japan, Thailand, Vietnam, Malaysia, South Africa, Singapore, Australia-New Zealand; Domestic: Andaman, Hyderabad, Kashmir, Darjeeling, Varanasi, Chandigarh, Goa, Jaipur, Kochi, Delhi & Dehradun.
· SOTC successfully managed a mega MICE movement in Bangkok, comprising 7,000 delegates from one of India’s leading pharmaceutical companies
Leisure Travel
· Expanded experiential outbound holidays, including iconic luxury rail journeys across South Africa, Canada, Australia, New Zealand and Egypt.
· Strengthened the luxury cruise portfolio with curated Antarctica, Arctic, Mediterranean and European cruise experiences.
· Introduced curated Fall and Winter holidays featuring Northern Lights, Arctic adventures, European Christmas markets and Alpine experiences.
· Expanded charter-led holiday offerings with Bengaluru–Lakshadweep and Mumbai–Bhutan departures announced for the upcoming season.
· Partnered with Abu Dhabi’s Department of Culture and Tourism to offer complimentary UAE entry visas on eligible holiday packages.
Destination Management Services (DMS) Network:
India DMS: SITA participated in Kerala Travel Mart, Kochi, from 24–27 September 2026, engaging with travel partners to exchange insights, explore emerging opportunities and strengthen collaborations to create compelling travel experiences across India, Sri Lanka, Nepal and Bhutan.
Overseas DMS: Revenue declined by 7% year-on-year in Q2 FY27, primarily due to continued geopolitical disruptions in the Middle East, which significantly impacted Desert Adventures and softer U.S. inbound tourism affecting Allied T Pro. The decline was partially offset by growth across Asian Trails and the Private Safaris businesses in East and Southern Africa.
o Asia Pacific – Asian Trails: Revenue grew 9% year-on-year, supported by positive performances in China, Singapore and Thailand, though growth was tempered by softer inflows from select source markets amid ongoing geopolitical uncertainties.
o USA – Allied T Pro: U.S. inbound tourism continued to face headwinds from softer international visitor arrivals and geopolitical uncertainties; hence the business saw sales lower by 22%. However, the extent of the decline moderated compared with the preceding quarter.
o Middle East – Desert Adventures: Performance remained significantly impacted by geopolitical uncertainties in the Middle East, which continued to weigh on travel demand during the seasonally weaker quarter. As a result, sales reduced by 67% y-o-y. While September witnessed early signs of improvement from key source markets, regional uncertainty continued to affect traveller confidence. The business maintained its focus on cost optimization and operational readiness, with encouraging forward booking trends, providing cautious optimism for the coming quarter.
o Private Safaris:
· Southern Africa: Revenue improved 31% year-on-year, powered by resilient inbound travel demand, with margin expansion driven by strategic upselling and stronger supplier negotiations, even against a backdrop of elevated airfares and constrained airline capacity.
· East Africa: Revenue recorded 10% year-on-year growth, led by sustained demand from key source markets, including the USA, Europe and India, despite some uncertainty affecting traveller confidence.

· Record Q2 revenue in the seasonally weakest quarter, with Revenue from Operations reaching ₹1,259 Mn, up 21% y-o-y, supported by stronger room demand, higher occupancy and improved pricing.
· Sustained profitability for 27 consecutive quarters, with EBITDA of ₹298 Mn and EBIT of ₹184 Mn, marking y-o-y growth of 4% and 1%, respectively, despite incremental cost pressures.
· Strong underlying operating performance, with room nights sold growing 23%, ARR increasing 9% to ₹6,484 and total RevPAR improving by 12%, reflecting broad-based growth across room and F&B revenues.
· Accelerated, capital-efficient portfolio expansion, with seven resorts opened during Q2 – the highest number in any quarter – taking the enterprise network to 83 resorts and crossing the milestone of 4,000 keys, with six additional sign-ups made during the quarter.
· Strong cash generation and a robust balance sheet, with cash reserves reaching ₹3,808 Mn, up 12% q-o-q. Sterling continued to remain debt-free and net cash-positive.
· Customer satisfaction strengthened further, with the TripAdvisor rating improving to 4.63 from 4.60 a year earlier, and 31 resorts ranking No. 1 in their respective areas.
· Awards:
o Sterling was named the “Fastest-growing Leisure Hotel Chain” at the Today’s Traveller Awards 2026 – for the third time in a row.
o Sterling ONE has been awarded “Smart Tech Enabled Platform of the Year 2026 – B2B” at the Indian Travel & Technology Summit & Awards 2026.

· Middle East operations (~ 50% of the portfolio) saw positive trends with almost all portfolio attractions restarting and currently functioning at ~40-50% levels. International visitors outlook through Q4 is the focus of the business.
· Capex deployment has been tightened, and the business continues its efforts to drive profitability growth through closure of non-profitable locations, optimization of commercial terms, and continued review of operating costs and capex deployment.
· 5 new partnerships signed: Malaysia (POP Morgan VR World, Snow World BTS), Maldives (Royal Island) and Singapore (The Palawan @ Sentosa) India (Mysore Water Park)
· Renewed 20 key partnerships: China: Shanghai Disney, Maldives (Le Meridien, Velassaru Maldives, Westin Miriandhoo, St. Regis), Indonesia (Ayodya Resort Bali, Bali Safari and Marine Park, Taman Safari Bogor, PT Taman Safari Indonesia II Jatim, Jumeirah Bali Resort, Conrad Bali), Malaysia (Penang Hill, Langkawi Wildlife Park, Langkawi Cable Car, KL Tower), UAE (Madinat Jumeirah Festive Market Event, Dubai World Cup 26–27, MEFCC 2026), Singapore (Singapore Flyer) Egypt (Snow City) and India (Ramoji Film City).
· Operational launch of 3 partnerships: Indonesia (Omma Day Club Bali), China (Shanghai Ocean Aquarium) and Maldives (Royal Island)
Other Key Business Updates
Focus on Digitalization
· AI-powered Chatbot with Dynamic Itinerary Customization (DynaPack): Enhanced the existing AI-powered chatbot with the integration of DynaPack, a customized itinerary feature currently in its initial phase. The enhanced bot can now generate real-time, personalized travel itineraries with dynamic pricing, enabling customers to explore tailored holiday options.
o India Network Expansion
Leisure Travel: Inaugurated 6 outlets across Thomas Cook India and SOTC in Q2 FY27 in Bengaluru, Gorakhpur, Ahmedabad, Chennai, Tirupati and Jamshedpur
· Awards and Partnerships
o Thomas Cook India’s Corporate Travel Team won “Best Corporate Travel Management Company of the Year 2026” at the Indian Travel & Technology Summit & Awards 2026
o Thomas Cook India’s Bhakti won “Best Spiritual & Pilgrimage Tour Operator” at the India Travel Awards 2026
o Thomas Cook India won ET MarTech Award for “Use of Generative AI in MarTech”
o Thomas Cook India won “Most popular tour operator” at the Mélange Awards 2026
o SOTC won “Best Travel Agency of the Year” and “Best Omnichannel Travel Agency of the Year” at the Indian Travel & Technology Summit & Awards 2026
o SOTC Travel awarded MICE & Travel Team of the Year at the MILT Excellence Awards 2026
About Thomas Cook (India) Limited:
Set up in 1881, Thomas Cook (India) Limited (TCIL) is the leading omnichannel travel company in the country offering a broad spectrum of services including Foreign Exchange, Corporate Travel, MICE, Leisure Travel, Value Added Services, and Visa Services. It operates leading B2C and B2B brands including Thomas Cook, SOTC, TCI, SITA, Asian Trails, Allied TPro, Australian Tours Management, Desert Adventures, Travel Circle International Limited (TCI 勝景遊), Sterling Holiday Resorts Limited, Distant Frontiers, TC Tours, Digiphoto Entertainment Imaging (DEI), Go Vacation, Private Safaris East & South Africa.
As one of the largest travel service provider networks headquartered in the Asia-Pacific region, The Thomas Cook India Group spans 28 countries across 5 continents.
TCIL has been felicitated with “Best Spiritual & Pilgrimage Tour Operator” at the India Travel Awards 2026, ET MarTech Award 2026 for “Use of Generative AI in Martech, ET Edge’s Best Organizations for Women (BOW) 2026, MICE Powerhouse at MaxiiiMICE Awards 2025, Outbound Travel Operator of the Year (2024) and MICE Travel Operator of the Year (2024 & 2023) at The Economic Times Travel & Tourism Annual Awards, MICE Travel Agency (Outbound) at the Economic Times MICE & Wedding Tourism Awards 2024, ‘Masters of Risk – Travel & Hospitality’ at India Risk Management Awards 2024, MICE Tour Operator of the Year – Outbound at SATTE 2024, Best Tour Operator at India Travel Awards North 2023, winner of the Corporate Citizen Award (Travel Tourism & Hospitality) at the Corporate Citizen Conclave & Award 2023, The Outbound Tour Operator of the Year 2022 at the SATTE Awards, IAMAI India Digital Awards 2022, CNBC-TV18 & ICICI Lombard India Risk Management Award – Travel & Leisure Category 2022 & 2021, CIO100 Award for digital innovation 2022.
CRISIL has reaffirmed the rating on debt programs and bank facilities of TCIL – ‘CRISIL AA/Stable’ on the long-term bank facilities of TCIL and ‘CRISIL A1+’ rating on the short-term bank facilities and short- term debt of the company. The highest rating for a travel & tourism company in India.
For more information, please visit www.thomascook.in
Fairbridge Capital (Mauritius) Limited, a subsidiary of Fairfax Financial Holdings Limited, is the promoter of TCIL with a shareholding of 64.77% of its paid-up capital.